Wise Account Explained: How to Open One, Fees and Where It Works (2026)
Wise account at a glance
- What it is: a Wise account lets you hold, convert, send and receive money in 40+ currencies at the mid-market exchange rate, with the fee shown before you pay.
- Where you can open one: you can register and send money from most countries, but you can only hold a balance if you live in a country on Wise’s list (US, UK, EEA, Canada, Australia, Brazil and others). India is travel-only; the UAE and Kenya are not named on the list.
- Cost: registering and holding money are free. Sending or converting starts at 0.23% in the US, 0.33% in India, 0.22% in the UAE and 0.52% in Kenya, depending on the currency.
- Receiving USD: local USD payments are free; a USD wire or Swift payment costs US$6.11 per payment.
- Card: available to personal customers in the US (one-time US$9), UK, EEA, Canada, Australia, Brazil and other listed countries. In India, Wise offers a Travel card instead.
- Best for: people who move money across currencies. If you only need a local bank account, Wise is not a replacement.
What is a Wise account, and what can you do with it?
Wise (formerly TransferWise) is a payments company authorised by the UK Financial Conduct Authority to issue electronic money. Instead of hiding a margin in the exchange rate, it uses the mid-market rate and charges a visible fee. A Wise account bundles four things:
| Feature | What it does | Where to check it |
|---|---|---|
| Send money | Transfer to bank accounts in 140+ countries; you see the fee, rate and recipient amount first | Quote on the send screen |
| Hold and convert | Keep balances in 40+ currencies and switch between them | Your account balances |
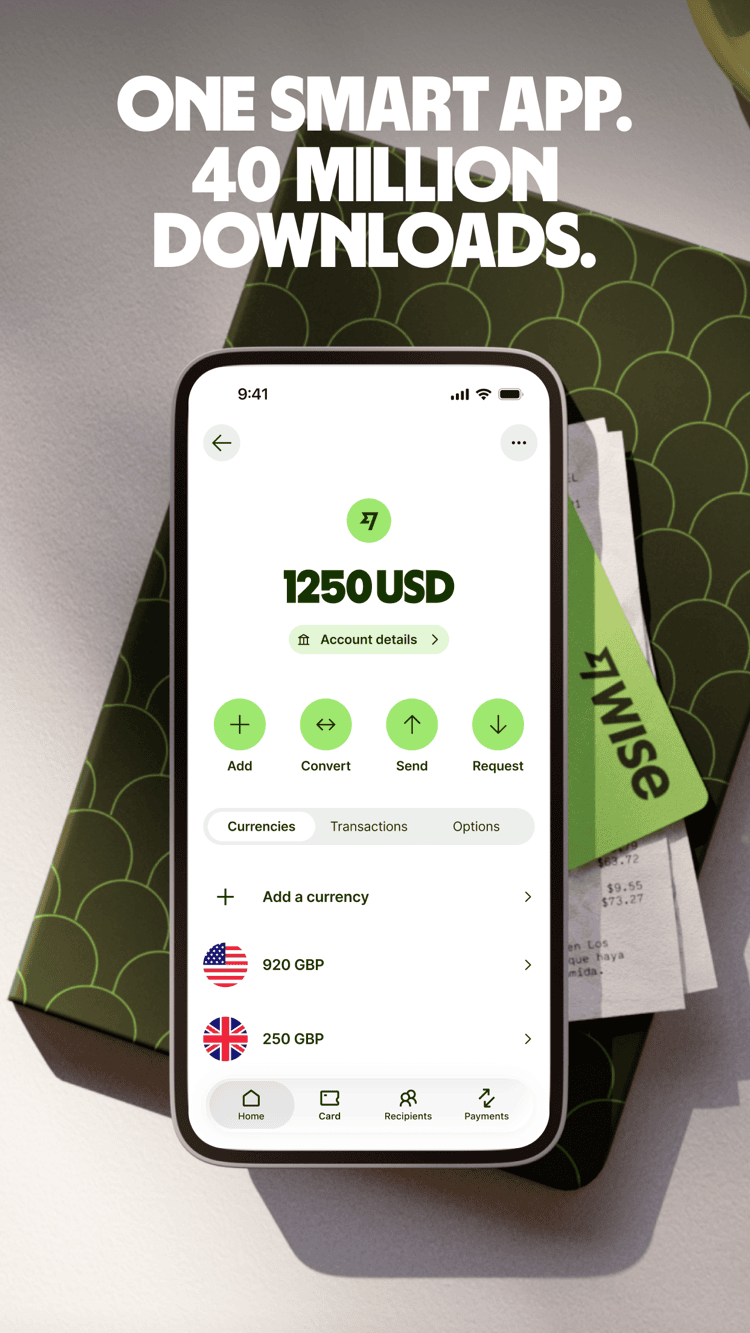
| Receive | Get local account details for some currencies and share them with clients or employers | Account details in the app |
| Card | Debit card and digital card for Google Pay / Apple Pay in eligible countries | Cards tab |
Can you open a Wise account where you live?
This is the question behind most “wise account” searches. Wise’s own Help Centre splits it in two: you can register and send money from most countries, but you can hold money only if you live in a country where Wise opens accounts. The table below uses Wise’s pages as of 25 October 2026.
| Where you live | Hold a balance? | Card | Sending fee from |
|---|---|---|---|
| United States | Yes (not in Nevada) | Yes, one-time US$9 (not Nevada) | 0.23% |
| United Kingdom | Yes | Yes | See the UK guide |
| EEA and Switzerland | Yes | Yes | Varies by route |
| Canada, Australia, Singapore, Japan | Yes | Yes | Varies by route |
| Brazil | Yes (BRL only if you live in Brazil) | Yes | From 0.4% |
| India | Only while travelling overseas | Wise Travel card, signed up with proof of travel | From 0.33% |
| United Arab Emirates | Not named on the hold-money list | Not on the card list | From 0.22% (see the UAE guide) |
| Kenya | Not named on the hold-money list | Not on the card list | From 0.52% |
If your country is not on the hold-money list you can still register, verify your identity and send money; you just cannot keep a Wise balance or get account details there. Wise does not serve a short list of countries at all, including Russia, Iran, Cuba and Syria, and it may restrict accounts used from them.
How to open a Wise account step by step
- Register on Wise with your email address and a password.
- Choose a personal account (or business, if the account is for a company) and select your country of residence.
- Add a phone number for two-step verification, then enter your legal name, date of birth and physical address.
- Verify your identity with the document Wise asks for; it may request more documents later.
- Add money with a bank transfer, debit card or the methods Wise shows for your country, or go straight to a transfer quote.
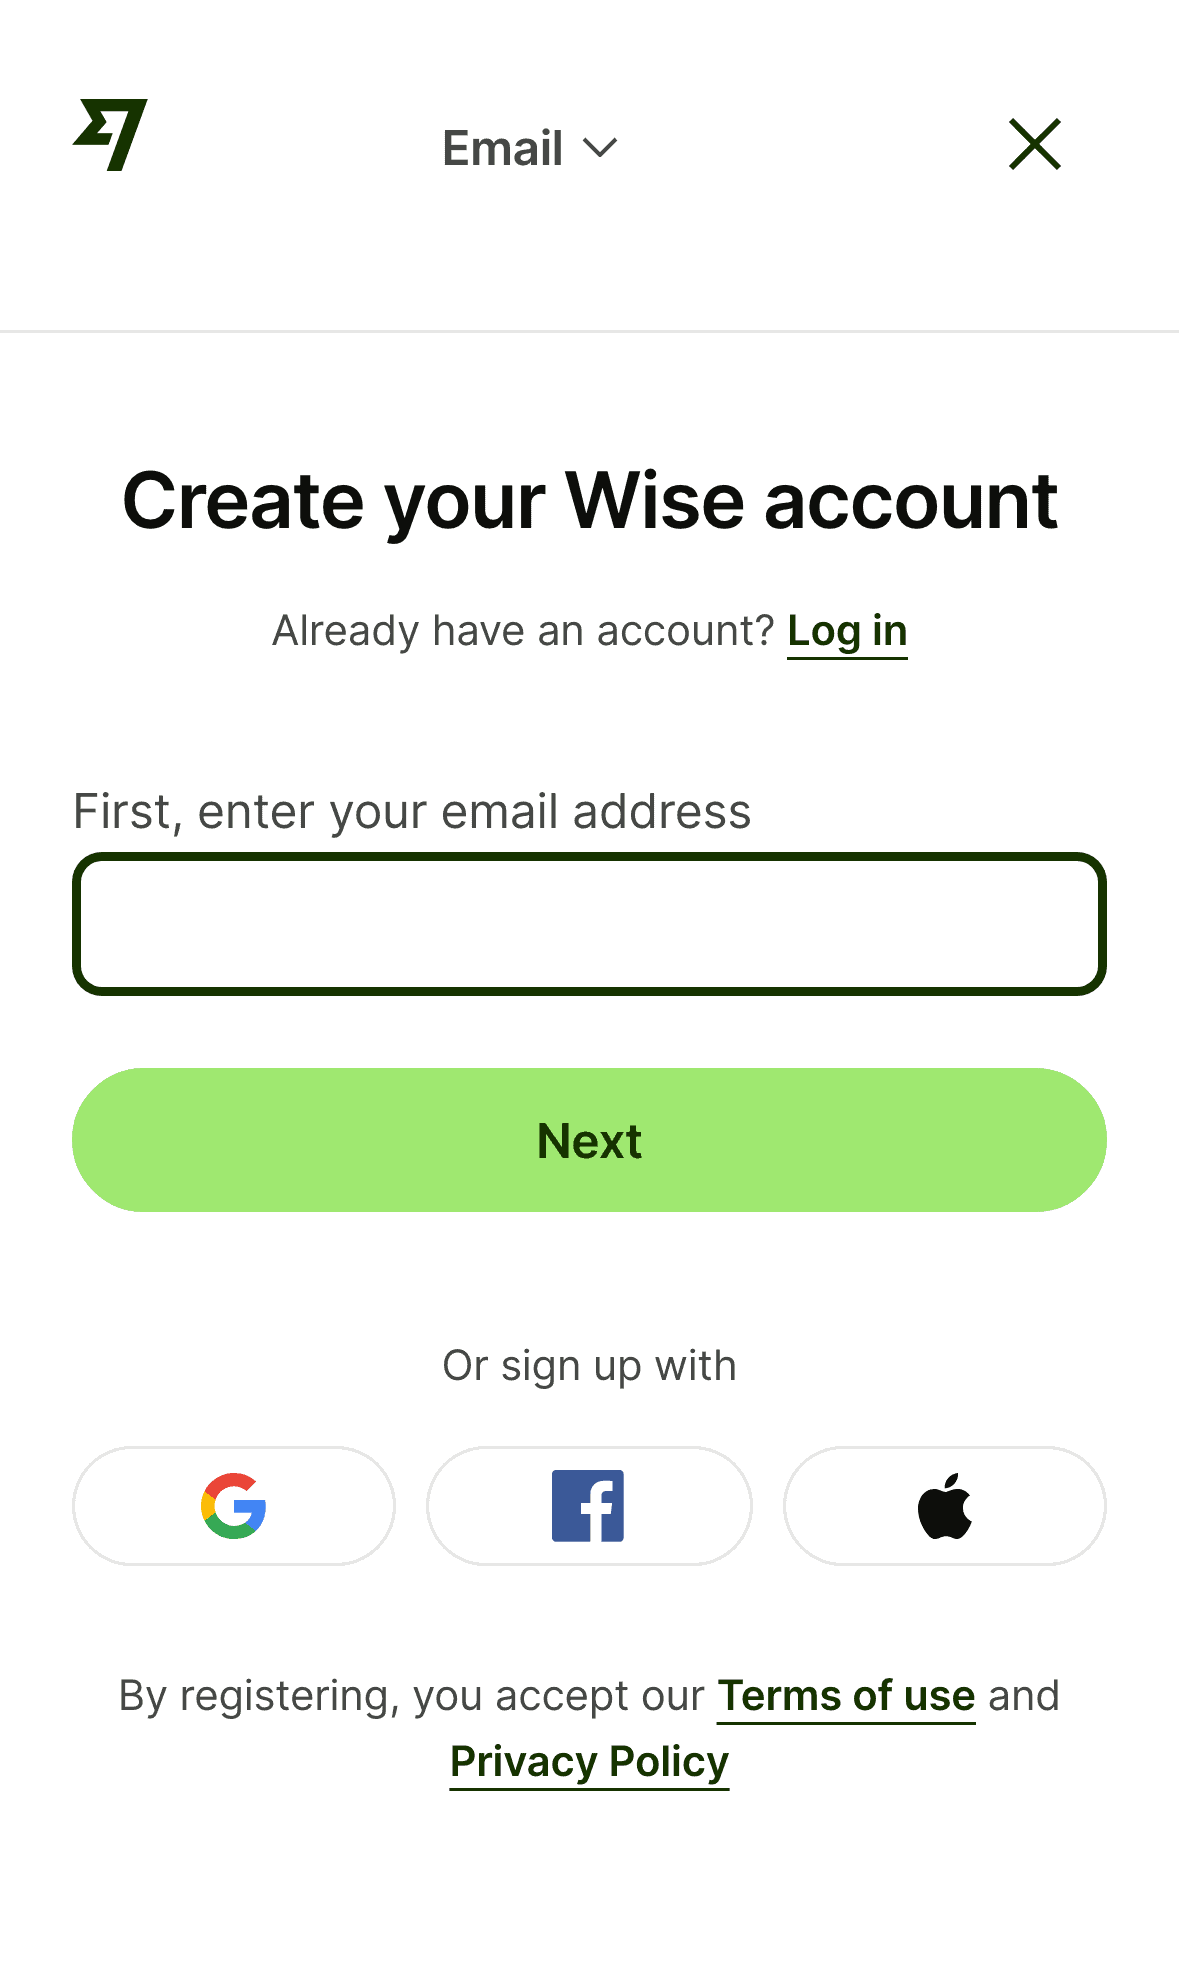
In India, the route starts differently: the Wise Travel card sign-up asks for proof of travel such as your passport and tickets, then you load INR and use the digital card while the physical card ships. Wise India says it is regulated by the Reserve Bank of India.
Before you verify: what to have ready
Identity checks are where most account problems start, and they are easier to clear before you need the money. Plan for the possibility of extra document requests, and finish verification early instead of on the day a payment is due.
- Register with your name exactly as it appears on the ID you will upload.
- Keep a recent bank statement or proof of address to hand in case a transfer is held for review.
- Verify before a trip or a deadline payment; a brand-new account is the wrong tool for a bill due tomorrow.
- Send a small test transfer first, then the full amount.
- Keep a second way to pay for anything time-critical until the account has run smoothly for a while.
The exact documents depend on your country and the route, so follow what the Wise app asks for rather than a checklist from another country.
Adding money to Wise: deposit by top-up or bank transfer
- Top-up in the app (Wise’s add-money guide): on Home choose Add money (or the currency, then Add), enter the amount, pick a payment method and follow the prompts.
- Bank transfer: copy the account details for that currency and send yourself money from your own bank. Wise treats it like someone else paying into your account.
- Check the fee first: look at the fee on the payment screen before you confirm. For BRL, Wise notes that IOF tax is charged when you add reais while paying in another currency.
What Wise costs: fees by market
| Item | US | India | UAE | Kenya |
|---|---|---|---|---|
| Register | Free | Free | Free | Free |
| Send / convert from | 0.23% | 0.33% | 0.22% | 0.52% |
| Card ATM allowance | US$250 per month free, then US$1.95 + 1.95% | US$200 per month free, then US$1.40 + 3.25% of the excess | — | — |
| Physical card | US$9 one-time | Travel card | — | — |
The figures above come from Wise’s US pricing page and the India, UAE and Kenya pages. Receiving money is free by local rail for AUD, CAD, EUR, GBP, HUF, NZD, PHP, SGD and USD. A USD wire or Swift payment costs US$6.11, GBP Swift £2.16 and EUR Swift €2.39. Sending the same currency between two Wise contacts is free. Topping up an external e-wallet in some currencies costs 2%.
A worked example
Say you invoice US$1,500 a month. By local USD rail you receive it for free; asking the client for a wire costs US$6.11 a time, so US$73.32 a year. Moving to another currency adds the conversion fee shown on the quote (the 0.23%–0.52% “from” figures are floors, not typical totals), so compare the recipient amount, not the headline percentage.
How to send money with Wise
- Pick the amount and the sending and receiving currencies.
- Read the fee, the rate and the amount the recipient gets, plus the estimated arrival time.
- Enter the recipient’s bank details (IBAN, routing number, sort code or the local format).
- Pay by bank transfer, debit card or the method offered, then follow the transfer in the app.
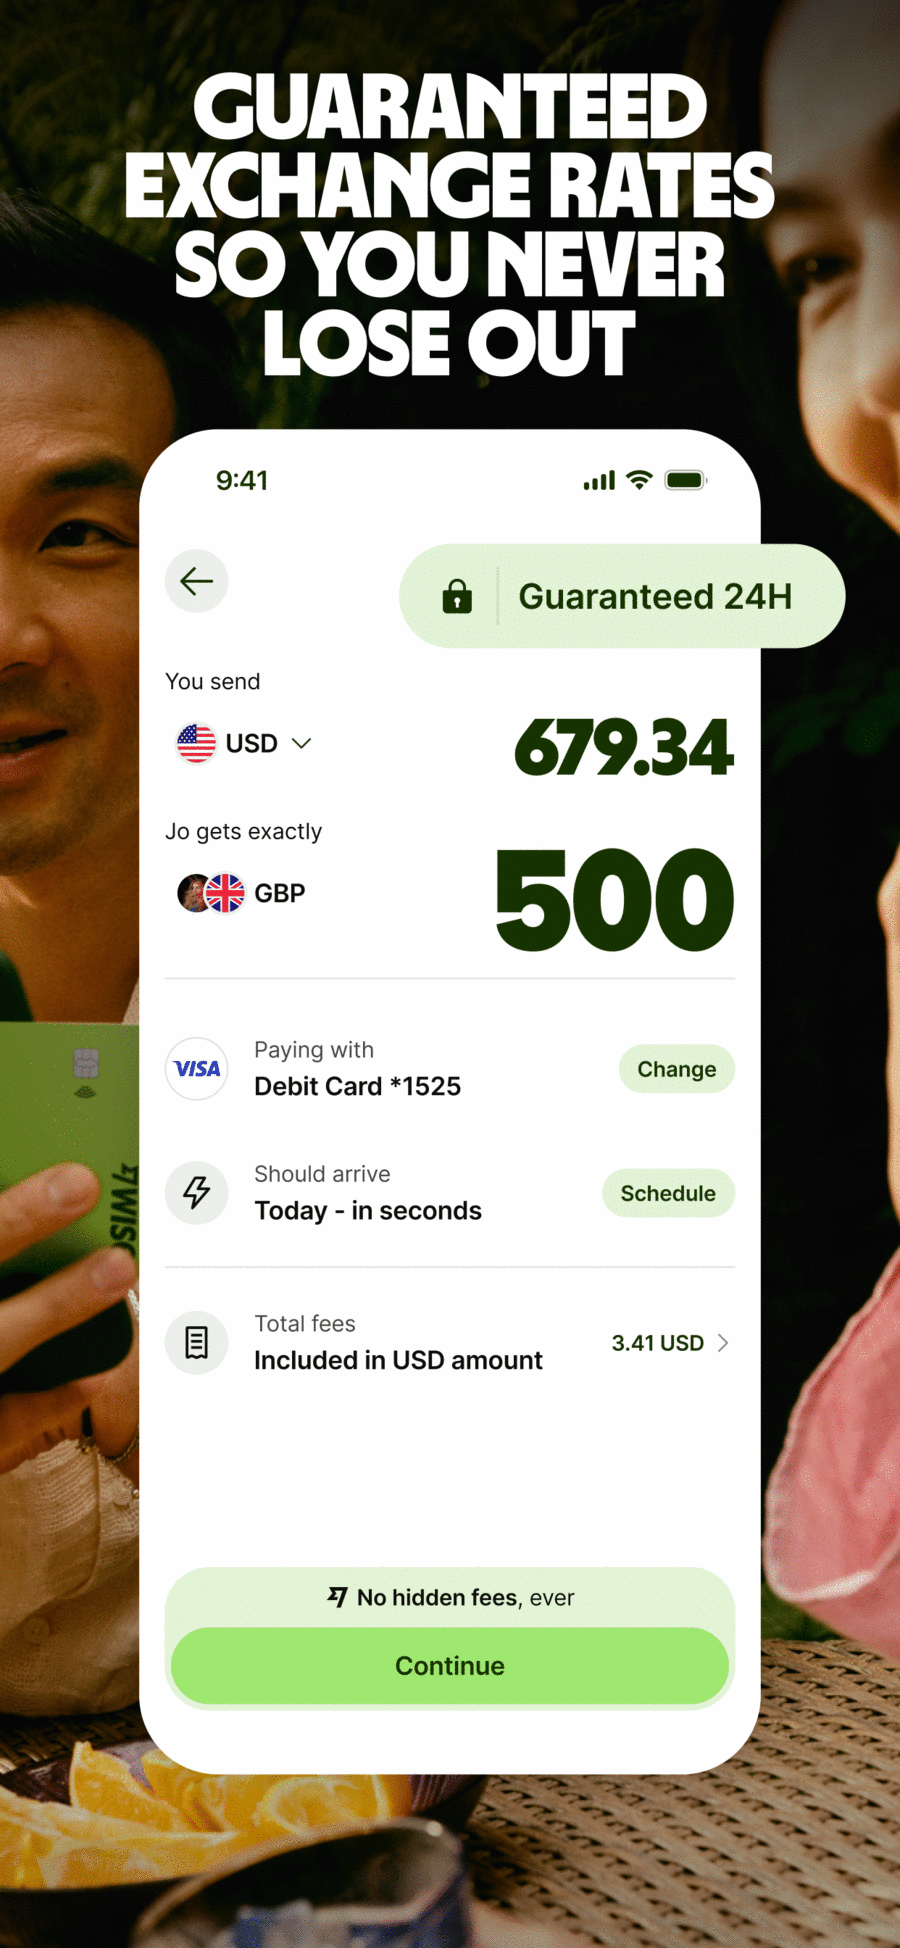
Wise says it never marks up the exchange rate, and the rate can still move before the money is converted. For a deadline payment, send a small test amount first.
Receiving money: account details for freelancers and employers
The most practical reason to hold a Wise balance is being paid like a local. In the app you open the balance for the currency you need, copy its account details and share them with the client or employer. Local receiving is free for AUD, CAD, EUR, GBP, HUF, NZD, PHP, SGD and USD; a USD wire or Swift payment costs US$6.11.
- Open the balance for the currency you are paid in (only available if you live in a country on the hold-money list).
- Share that currency’s account details and ask the payer to send a local transfer, not a wire.
- Convert to another currency only when the quote suits you; the fee and the amount you get are shown first.
- If the payer insists on a wire, plan around the US$6.11 fee from the worked example above.
Wise card: who can get one and what it costs
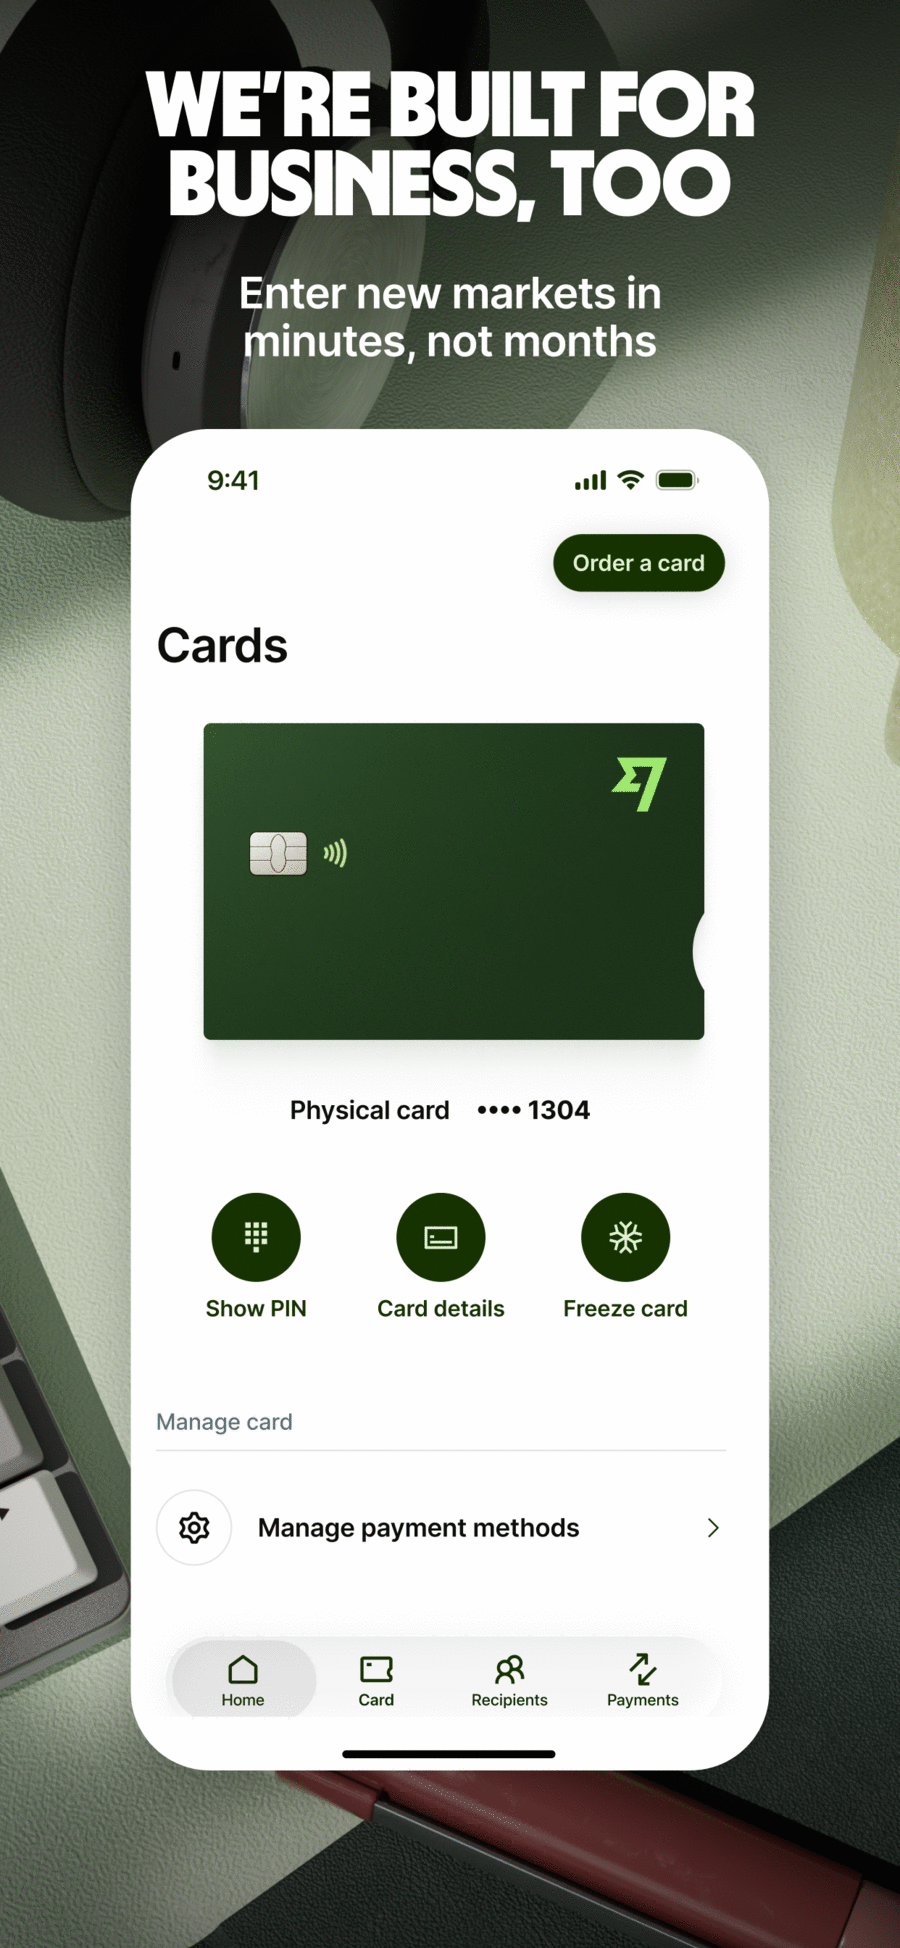
Personal customers who live in Australia, Brazil, Canada, the EEA and Switzerland, Israel, Japan, Malaysia, New Zealand, the Philippines, Singapore, Thailand (accounts opened on or after 21 January 2026), the UK and the USA (except Nevada) can get a Wise card (Wise’s country list). You can freeze and unfreeze it instantly, and a digital card works in Google Pay or Apple Pay right away. If your country is not listed, Wise runs a waitlist.
Who Wise suits and who it does not
| Good fit | Poor fit |
|---|---|
| Freelancers paid in USD, EUR or GBP | Anyone who needs a full local bank account |
| Students and expats paying fees abroad | Readers in countries Wise does not support for accounts, who can send money but not hold it |
| Travellers who convert before a trip | Cash-heavy spenders: ATM use beyond the free allowance costs extra |
Wise or your bank? What to compare
Wise is not always the cheaper route, so put the same questions to your bank before you choose. The comparison below lists what Wise states and what to ask at the bank.
| Question | What Wise states | What to ask your bank |
|---|---|---|
| Fee | Shown on the quote before you confirm | Your bank’s fee and any fee charged by the receiving bank, in writing |
| Exchange rate | Wise says it uses the mid-market rate only | Which rate and margin applies to your amount |
| Holding foreign currency | Balances in 40+ currencies if you live in a listed country | Whether a foreign-currency account exists and what it costs |
| Receiving from abroad | Local account details for some currencies | Whether incoming wires carry a fee |
If the total that arrives is within a few percent either way, pick the option you can verify and track most easily.
Where to go next depending on your question:
- Wise vs Revolut: fees and features side by side if you are choosing between the two.
- Revolut review: what Revolut adds and where it is limited.
- Wise Philippines guide: a market where the card is now available.
Frequently asked questions
Can I open a Wise account from India, the UAE or Kenya?
You can register and send money from these countries. Holding a full multi-currency balance requires living in a country on Wise’s list; India is limited to travel use and the UAE and Kenya are not named on the list as of 25 October 2026. India has the Wise Travel card.
How does Wise work?
You create an account, verify your identity, add money and either send it or convert it. Wise uses the mid-market rate and shows its fee and the recipient amount before you confirm.
Is Wise legal in the USA?
US residents can open a Wise account: the United States is on Wise’s hold-money and card lists, except Nevada. Wise’s site footer names the UK FCA authorisation for its e-money services.
Can I use Wise like a normal bank account?
Not entirely. It is built for holding and moving money across currencies; a local bank account is still useful for everyday local needs.
Can US citizens have a Wise account?
If you live in the United States, yes (not Nevada). Residence, not citizenship, decides where you can hold money.
What is the downside of Wise?
Fees still apply (from 0.23% in the US), ATM withdrawals beyond the free allowance cost extra, a USD wire costs US$6.11 to receive, and you can only hold money if you live in a supported country.
Can I get a Wise card in India?
Not the standard card. Wise India offers the Wise Travel card: you sign up with proof of travel such as your passport and tickets, load INR, use the digital card straight away and wait for the physical card to ship. Wise India also lists ATM withdrawals as free up to 200 USD a month, then 1.40 USD plus 3.25% of the amount over 200 USD.
Is a Wise account free?
Registering and holding money are free. You pay when you send or convert (from 0.23% in the US, depending on the currency), when you order the US card (a one-time US$9) and when you use the card at an ATM beyond the free allowance.
Last updated: 25 October 2026, from Wise’s official pricing, Help Centre and country pages. Fees and availability change, so the quote shown before you confirm is the final word.
Disclosure: some links in this guide are referral links. They cost you nothing extra and this site may earn a reward.